Payday arrives, and for a day or two, everything feels fine. Then rent leaves the account, the card payment follows, groceries, gas, a school cost, two subscriptions you barely remember signing up for, and suddenly you are counting the days to the next paycheck again. The strange part is that you cannot point to one big purchase that caused it.
That is not usually an income problem alone, and it is not a character problem. It is a planning problem. Money that has no job assigned to it tends to drift, a little at a time, until there is nothing left for the things that actually matter to you.
Personal finance sounds complicated, but at its heart it is one simple skill: deciding where your money will go before the month decides for you. That is what a budget is. This guide shows you how to build one that fits real American life, keep it going in about fifteen minutes a week, and use it to build real savings step by step.
What Budgeting Really Is (and What It Is Not)
A budget is a written plan for your take-home pay. It lists what must be paid, what you want to save, and what you can spend, in that order of honesty. A good budget is not a punishment and it is not about never enjoying anything again. If a plan removes every meal out, every gift, and every small pleasure, most people quit it within a month, and a plan you quit does nothing for you.
Think of budgeting the way you think of a map on a long drive. You can still choose stops along the way. You are simply no longer guessing where you will end up.
Why budgets fail in the first month
Most budgets do not fail because the math was wrong. They fail because they were built on a guess of what someone thought they spent, instead of what they actually spent. They also fail when they forget irregular bills, leave no room for fun, or try to change ten habits at once. Every step below is designed to avoid exactly those traps.
Step 1: Know Your Real Monthly Income
Start with the amount that actually lands in your bank account, not your salary before tax. If you are paid every two weeks, remember that most months contain two paychecks, but two months a year contain three. That small detail matters, and many people never plan for it.
If your income changes from month to month, for example with shifts, tips, commissions, or freelance work, do not budget from your best month. Look at your last three to six months and build the plan from a lower, more typical month. Money that arrives above that baseline can then be assigned on purpose, toward savings, debt, or a goal, instead of disappearing.
Step 2: Track What You Actually Spend for One Month
Before cutting anything, observe. For one month, or by reviewing your last two or three bank and card statements today, sort your spending into groups: housing, utilities, groceries, eating out, transport, insurance, debt payments, subscriptions, personal items, and everything else.
Most people find at least one surprise in this step, and it is usually not a large item. It is frequency: the small deliveries, the top-up shops between big grocery trips, the services still charging every month. Write your real numbers down, without judging them. You cannot improve a number you refuse to look at, and almost everyone who does this exercise finds money they did not know they were losing.
Step 3: Choose a Budgeting Method You Can Repeat
There is no single correct method. There are three well-known approaches, and the best one for you is simply the one that matches how your brain and your household work.
The 50/30/20 guideline
This popular framework suggests aiming for roughly 50 percent of take-home pay on needs, 30 percent on wants, and 20 percent on savings and extra debt payments. Treat it as a compass, not a law. In high-rent cities, needs may honestly take more than half of income for a while. In that case the guideline still helps, because it shows you clearly which side of the plan needs attention first.
The zero-based budget
Here, every dollar of income is given an assignment, so income minus planned spending and saving equals zero. Zero-based does not mean spending everything. It means nothing is left unassigned to drift. This method suits people who like detail and control, and it works well with a notebook, spreadsheet, or budgeting app.
The envelope and category method
With envelopes, you set a spending limit for flexible categories such as groceries, eating out, and fuel. Traditionally this used cash in labeled envelopes, and some people still prefer cash because it is visible and finite. Others use separate accounts or an app that creates digital categories, such as Goodbudget, or a full budgeting app such as YNAB or EveryDollar. If you try an app, check whether it is free or paid before you commit, because prices and features change. A simple spreadsheet or paper notebook remains a perfectly valid tool, and free budgeting worksheets are also published by the Consumer Financial Protection Bureau at consumerfinance.gov.
Step 4: Build a Bill Calendar So Nothing Surprises You
Late fees and overdraft stress often come from timing, not totals. A bill can be affordable and still cause a problem if three large bills leave the account in the same week as rent.
Make a simple calendar of every regular bill and its due date: rent or mortgage, utilities, phone, insurance, loan and card payments, and subscriptions. Then look at the pattern across the month. If your due dates are badly bunched, some companies allow customers to request a different due date. It never hurts to ask politely. At minimum, your calendar tells you how much of each paycheck is already spoken for before you spend anything from it.
Step 5: Pay Yourself First, Automatically
This is the habit that separates people who intend to save from people who actually save. “Pay yourself first” means moving money to savings at the start of the pay cycle, on payday itself, rather than saving whatever happens to be left at the end. For most people, what is left at the end is close to zero, no matter what they intended.
Set up an automatic transfer to a separate savings account for the day your pay arrives. Starting small and consistent is far better than starting large and quitting. Keeping savings in a separate account, ideally at a different bank or at least out of your everyday view, reduces the temptation to dip into it. If you open a savings account, check that the bank is FDIC insured or the credit union is NCUA insured, and compare fees and interest rates, which vary and change over time.
Step 6: Give Your Grocery and Food Spending a Real Plan
For most households, food is the largest flexible cost, and that makes it the largest opportunity. You do not need extreme couponing. Three plain habits do most of the work: plan several dinners before you shop, shop with a list built from that plan, and check what you already have at home so you stop buying duplicates.
Eating out deserves its own honest line in the budget too, including delivery fees and tips, which quietly turn a modest meal into an expensive one. Many families find that setting a clear monthly eating-out amount, and enjoying it without guilt inside that amount, works far better than banning it and then breaking the rule in week two.
Step 7: Build an Emergency Fund in Stages
An emergency fund is money set aside for true surprises: a car repair, a medical bill, an appliance failure, or a sudden drop in income. Without one, every surprise becomes card debt, and the budget has to start over.
Build it in stages so the goal never feels impossible. The first stage is a small starter fund that can handle a minor emergency. The next stage many financial educators discuss is one month of essential expenses, then gradually more over time as your situation allows. There is no single correct final number for everyone. Your stage depends on your job stability, household, and responsibilities, and growing it steadily matters more than reaching any particular figure quickly.
Step 8: The Budget Line Most People Miss — Sinking Funds
Here is the curiosity item our videos mention, and once you see it, you cannot unsee it. Some of your biggest expenses are not monthly, so they never appear in a normal monthly budget, until the month they land all at once and wreck it. Car insurance billed every six months. Vehicle registration. Annual subscriptions. School supplies. Holidays and birthdays. A new set of tires you knew was coming.
These are not emergencies. They are predictable. A sinking fund is how you budget for them: estimate the yearly cost, divide it by twelve, and set that small amount aside every month in a labeled category, envelope, or savings sub-account. When the bill arrives, the money is already waiting, and a “surprise” bill becomes a non-event.
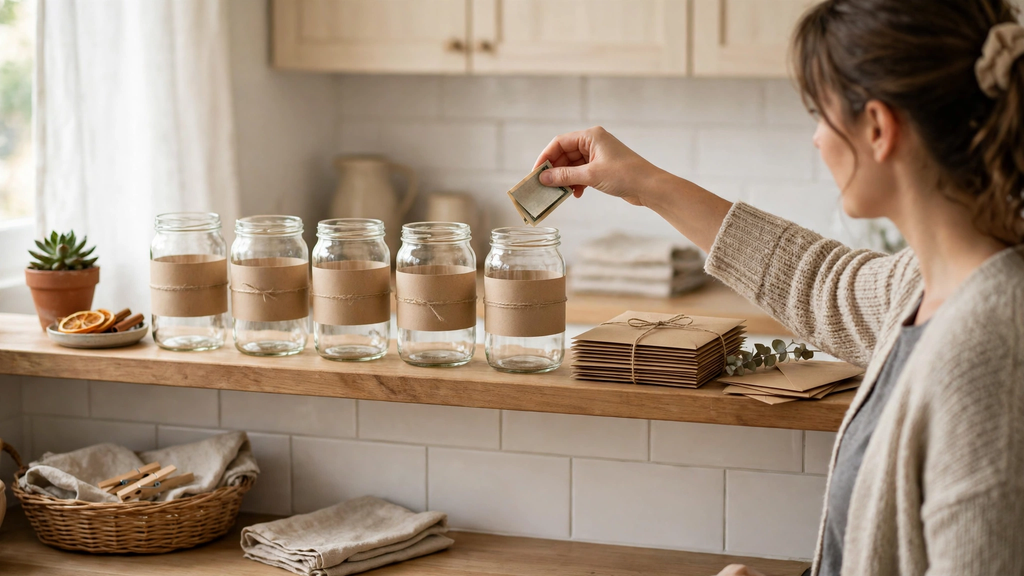
Start with just two or three sinking funds: the ones that have hurt you before. Add more gradually. This single habit is often the difference between a budget that survives the year and one that collapses every December.
Step 9: Hold a Fifteen-Minute Weekly Money Check
Budgets are not maintained once a month. They are maintained in small, regular check-ins. Pick one fixed time each week, put the kettle on, and spend fifteen minutes on four questions. What came in? What went out that was not planned? What is due before the next paycheck? Does any category need a small adjustment?
If you budget with a partner, do this check together, briefly and without blame. Money conversations go better as short, regular planning sessions than as long arguments after something has gone wrong. Once a month, do a slightly longer review: compare your actual spending with your plan, move one small step forward on savings or debt, and update next month’s numbers based on what you learned.
Budgeting on an Irregular Income
If your pay changes every month, add one extra rule: pay your essentials in a fixed priority order. Housing, utilities, groceries, transport to work, insurance, and minimum payments come first, in that kind of order. Only when essentials are covered do variable categories get filled, and in stronger months, fill your emergency fund and sinking funds first. This priority list removes the daily stress of deciding what matters, because you decided it once, in advance, while calm.
Common Budgeting Mistakes to Avoid
The first mistake is building a budget from hoped-for spending instead of real spending, which is why the tracking step comes first. The second is forgetting irregular expenses, which sinking funds solve. The third is setting no money aside for enjoyment and then abandoning the plan entirely. The fourth is keeping savings in the same everyday account, where it silently gets spent. And the final mistake is treating one bad week as failure. A budget is adjusted, not abandoned. Everyone overspends sometimes. The people who succeed financially are the ones who correct course the following week and continue.
Final Word: A Budget Is Freedom Planned in Advance
Budgeting is not about saying no to your life. It is about saying yes on purpose: yes to the bills being covered, yes to the insurance bill that no longer scares you, yes to savings that grow quietly every payday, and yes to spending on things you enjoy without the guilt that comes from guessing.
Start this week with the simplest version. Write down your real income, track one month honestly, automate one small transfer on payday, and open your first sinking fund. Four small steps, repeated, are what personal finance success actually looks like from the inside.
